Money is part of almost every decision we make. We use it for groceries, rent, bills, travel, entertainment, family needs, future plans, and the occasional purchase we probably did not plan for.Yet managing money well is not always about earning a huge salary. Good money management is more about knowing where your money goes, making thoughtful choices, and building habits that make everyday life easier.You do not need a complicated spreadsheet or a perfect financial plan to get started. Sometimes, it begins with something as simple as checking your bank balance regularly or asking yourself, “Do I actually need this?”The goal is not to stop enjoying your money. It is to spend with purpose, save consistently, and give yourself more financial breathing room.
What Is Money Management?
Money management means taking control of how you earn, spend, save, borrow, and plan your money.
It includes everyday decisions, such as managing monthly expenses, as well as longer-term goals like building an emergency fund, reducing debt, investing, or saving for a major purchase.Think of it like managing your time. If you never look at where your hours are going, the day can disappear quickly. Money can work in much the same way.Small expenses can quietly add up.A coffee here, a food delivery there, a subscription you forgot about, and a few impulse purchases can eventually become a surprisingly large amount.Awareness is the first step toward better financial habits.
Why Money Management Matters
Having a money plan can make everyday financial decisions feel less stressful.
When you know how much you earn and what your regular expenses look like, it becomes easier to decide what you can realistically afford.
Good money management can help you:
- Control unnecessary spending
- Build savings
- Prepare for unexpected expenses
- Manage debt
- Plan larger purchases
- Work toward financial goals
- Reduce money-related stress
- Develop healthier spending habits
It is not about being perfect. It is about becoming more intentional with your money.
Start by Understanding Your Income
Before creating a budget, understand what actually comes into your account each month.
Your income may include:
- Salary
- Freelance income
- Business income
- Rental income
- Bonuses
- Side-income sources
- Other regular earnings
If your income changes from month to month, using a conservative estimate can make your budget more realistic.For example, if your monthly income varies between ₹40,000 and ₹55,000, you might build your basic spending plan around the lower amount rather than assuming you will always receive ₹55,000.A realistic budget is much easier to maintain than an overly optimistic one.
Track Where Your Money Goes
This is one of the simplest—and sometimes most revealing—money habits.
For one month, write down your expenses. You can use a notebook, spreadsheet, budgeting app, or even a basic note on your phone.
Divide your spending into categories such as:
| Category | Examples |
|---|---|
| Housing | Rent, mortgage, maintenance |
| Food | Groceries, restaurants, delivery |
| Transport | Fuel, public transport, repairs |
| Utilities | Electricity, water, internet |
| Personal | Clothing, hobbies, beauty |
| Entertainment | Movies, games, outings |
| Financial | Savings, investments, debt payments |
After a month, look at the numbers without judging yourself.
You may discover that one category is taking up much more money than you expected.
That little moment of surprise can actually be useful.
Create a Budget That Fits Real Life
A budget should guide your money, not make you feel trapped.
A common approach is to divide income between needs, wants, savings, and financial goals. The exact percentages do not need to be identical for everyone.
For one person, housing may consume a large portion of income. Someone else may have lower housing costs but higher education or family expenses.
That is why there is no magic budget that works perfectly for every household.
The best budget is one you can realistically follow.
Start with your essential expenses, then decide how much you want to put toward savings and financial goals. Whatever remains can be allocated to flexible spending.
Separate Needs From Wants
This sounds simple, but it can be surprisingly difficult.
A need is something essential for everyday life, such as basic food, housing, utilities, or necessary transportation.
A want is something that improves your lifestyle but is not essential.
The tricky part is that the line can sometimes move.
For example, replacing a completely broken phone may be a need if you rely on it for work. Buying the newest model simply because it has a slightly better camera may be more of a want.
Before making a purchase, pause for a moment and ask whether it solves a real problem or simply creates a temporary feeling of excitement.
That small pause can prevent plenty of unnecessary purchases.
Build an Emergency Fund
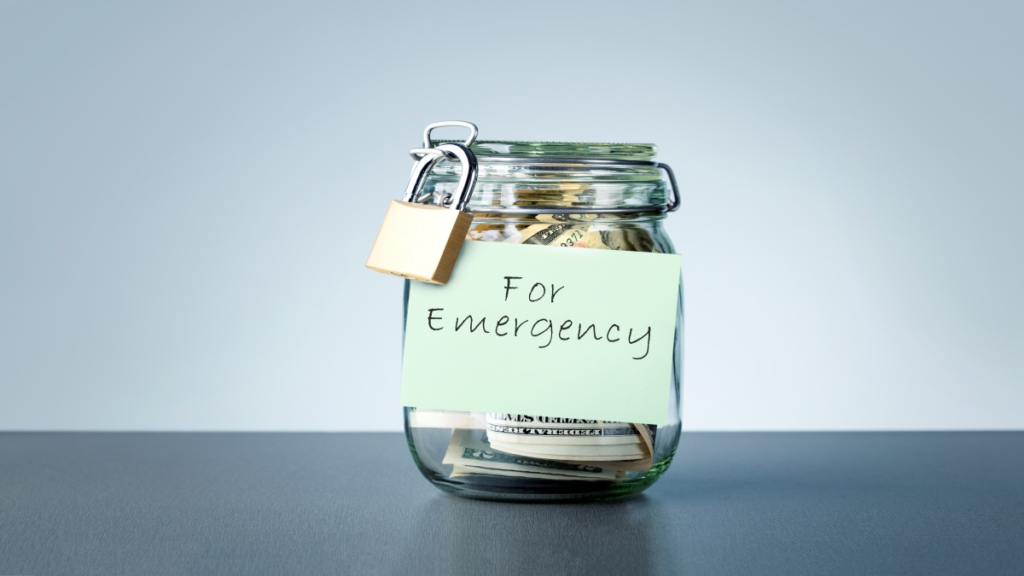
Life rarely follows the plan.
A medical bill, car repair, job change, broken appliance, or unexpected family expense can appear when you least expect it.
An emergency fund provides a financial cushion for situations like these.
Instead of trying to build a large amount overnight, start small.
Even setting aside a modest amount every month can create a useful safety net over time.
Consistency matters more than starting with a perfect amount.
Keep emergency savings somewhere accessible and separate from your everyday spending money so you are less tempted to use it for routine purchases.
Make Saving Automatic
Saving becomes easier when you do not have to remember to do it every month.
Consider setting up an automatic transfer shortly after receiving your income.
For example, if you decide to save ₹5,000 each month, an automatic transfer can move that amount into your savings account before you have a chance to spend it.
This is sometimes called “paying yourself first.”
The idea is straightforward: treat saving as a regular financial responsibility rather than something you do only when money happens to be left over.
Watch Your Subscriptions
Subscriptions are easy to start and surprisingly easy to forget.
Streaming services, apps, memberships, cloud storage, gaming subscriptions, and other recurring payments can quietly continue for months.
Take a few minutes every couple of months to review them.
Ask:
- Do I still use this?
- Does it provide enough value?
- Am I paying for similar services?
- Could I switch to a cheaper plan?
- Can I cancel something I rarely use?
You do not need to cancel everything fun.
The point is to make sure your recurring expenses still match your current lifestyle.
Be Careful With Impulse Spending
Impulse purchases are not always expensive.
Sometimes the problem is the frequency.
A ₹300 purchase may not seem important. But several small purchases every week can become a meaningful monthly expense.
Try using a simple waiting rule for non-essential purchases.
For something inexpensive, wait a day. For a larger purchase, give yourself several days to think about it.
You may still decide to buy it—and that is perfectly fine.
The difference is that you are choosing the purchase rather than reacting to the moment.
Manage Debt Carefully
Debt can be useful when handled responsibly, but high-interest debt can make financial progress much harder.
Start by understanding:
- How much you owe
- Interest rates
- Minimum payments
- Due dates
- Total repayment costs
Missing payments can potentially lead to additional charges and other financial consequences, depending on the type of debt and lender.
If you have multiple debts, you can explore different repayment approaches, such as focusing on the highest-interest debt first or paying smaller balances first for motivational reasons.
The important thing is to have a clear repayment strategy rather than letting debt become something you avoid looking at.
Learn the Difference Between Saving and Investing
Saving and investing are related, but they serve different purposes.
Savings are generally useful for short-term needs and emergency funds. Investing is typically associated with longer-term financial goals and involves the possibility of losing money as well as gaining it.
Before investing, understand what you are buying, what risks are involved, and whether the investment matches your goals and time horizon.
Do not invest simply because someone online says an opportunity is guaranteed.
There is no shortcut that removes investment risk.
If you are unsure about a financial product or investment decision, consider speaking with a qualified financial professional.
Set Specific Financial Goals
“Save more money” is a good intention, but it is not a very specific goal.
Instead, give your goal a number and a timeframe.
For example:
- Save ₹30,000 for an emergency fund
- Save ₹60,000 for a vacation
- Pay off a particular debt within a set period
- Build a house deposit
- Save for education
- Increase monthly investments
A specific goal gives your money a purpose.
And honestly, saving feels different when you know what you are saving for.
Use the 24-Hour Rule
Found something you really want online?
Put it in your cart and walk away.
Wait 24 hours before buying.
For larger purchases, you can wait even longer.
This simple habit gives your brain time to move past the initial excitement.
Sometimes you return the next day and think, “Why did I even want that?”
Other times, you still want it—and you can buy it knowing that the decision was more deliberate.
Avoid Lifestyle Inflation
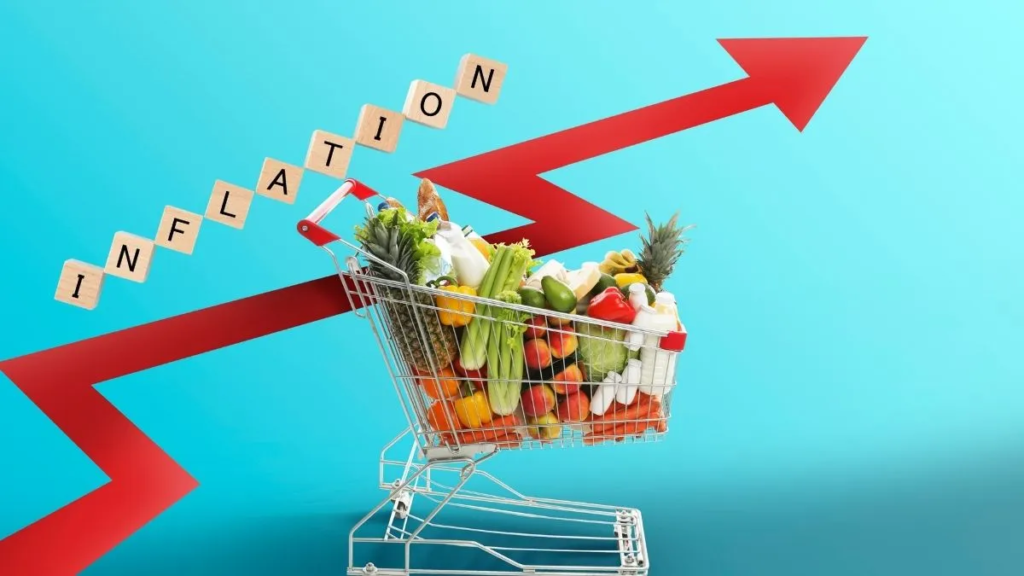
As income increases, it is natural to improve your lifestyle.
Maybe you move to a nicer home, eat out more often, travel more, or upgrade your gadgets.
There is nothing inherently wrong with enjoying higher income.
The problem comes when every increase in income immediately becomes an increase in spending.
If your salary rises, consider directing part of that increase toward savings, investments, debt repayment, or other financial goals before increasing your regular expenses.
That way, your lifestyle can improve without your financial responsibilities growing at exactly the same speed.
Have Money Conversations at Home
Money can sometimes be an uncomfortable topic between partners or family members.
But avoiding the conversation rarely makes financial planning easier.
Talk openly about:
- Monthly expenses
- Savings goals
- Major purchases
- Debt
- Shared responsibilities
- Long-term plans
You do not have to agree on every financial decision.
What matters is understanding each other’s priorities and creating a plan that works for the household.
Review Your Money Plan Regularly
Your financial situation can change.
You might get a new job, move to a different city, take on new responsibilities, pay off a loan, or start a family.
That means your budget should not be treated like a document that never changes.
Review your money plan every few months.
Ask yourself:
What is working? What is costing too much? What has changed? What should I adjust?
A short review can help keep your financial habits connected to your current life.
Simple Money Habits That Can Make a Difference
You do not need to transform your finances overnight.
Start with a few practical habits:
- Check your spending regularly
- Create a realistic monthly budget
- Automate savings
- Review subscriptions
- Build an emergency fund
- Avoid unnecessary high-interest debt
- Compare prices before major purchases
- Set clear financial goals
- Give yourself time before impulse purchases
- Review your financial plan regularly
These habits may sound ordinary, but ordinary habits repeated consistently can create meaningful changes over time.
FAQ’S
1. What is money management?
Money management is the process of earning, budgeting, spending, saving, and planning your money to support your current needs and future financial goals.
2. Why is money management important?
Good money management can help you control spending, build savings, prepare for unexpected expenses, manage debt, and work toward long-term financial goals.
3. How can I start managing my money better?
start by tracking your income and expenses, creating a realistic budget, reducing unnecessary spending, and setting aside money regularly for savings.
4. How much money should I save each month?
There is no single amount that works for everyone. Consider your income, essential expenses, debt, financial goals, and emergency needs when deciding how much to save.
5. What is an emergency fund?
An emergency fund is money kept aside for unexpected expenses such as urgent repairs, medical costs, or temporary income loss.